Closing the Loop in Smart Maintenance: Who Gets From Alert to Repair
- Zeynep Kaman
- 460 reads
IoT Analytics sizes smart maintenance at $8.1B in 2025, rising to $20.4B by 2032. Most vendors cover only part of the alert-to-repair loop.
Ask a maintenance lead what the next big gain is, and the answer is rarely a better sensor. It's the handoff. A vibration sensor flags a bearing, an analytics tool guesses the failure mode, and then the alert sits in an inbox while someone decides whether it's worth a work order. Closing that gap, from the first alert through the completed repair and back into the model, has become the central theme in smart maintenance. It came up repeatedly at maintenance and asset performance trade fairs, and in more than 75 interviews IoT Analytics conducted with vendors and adopters.
Here's the thing: the loop almost never closes inside one company's product. Sensor specialists, analytics vendors and maintenance software providers each cover a slice of it. They're tying those slices together through integrations, partnerships and acquisitions, and the pattern of those deals says a lot about where the market is heading.
How big the market is and where it's growing
IoT Analytics estimates the global smart maintenance market reached $8.1 billion in 2025. Its 376-page Smart Maintenance & Asset Performance Market Report 2026–2032, published in November 2026, projects a 14% CAGR to $20.4 billion by 2032. That's about 2.5 times the 2025 size. Baker Hughes, IBM and Emerson lead a fragmented field in which no single vendor holds more than 6%.
Wireless sensing is the fastest-growing piece. It's forecast to climb from $1.1 billion in 2025 to $5.1 billion by 2032, a 24% CAGR, and to become the largest segment by 2032. Wireless specialists I-care, AssetWatch and Tractian are gaining share in that segment, while several automation incumbents are losing it. Standalone predictive and prescriptive analytics is also expanding quickly. Sensor shipments reached 4.1 million units in 2025 and are expected to grow 16% a year through 2032.
The sizing follows a specific scope. IoT Analytics defines smart maintenance as digital and connected solutions, plus directly related services, that support industrial asset maintenance across monitoring, diagnosis, maintenance action and reliability improvement. The core covers three asset monitoring categories (wireless, wired and portable sensing, including bundled software and services) and three maintenance software categories: standalone analytics, asset performance management (APM) and computerized maintenance management systems (CMMS). Standalone managed monitoring and reliability consulting sit outside it, as do EAM, ERP and MES. The estimates rest on interviews with more than 75 experts, two surveys of 120 end users each, and visits to four trade fairs, including Hannover Messe and IMTS 2026.
What downtime actually costs
IoT Analytics puts unplanned downtime at $0.5 trillion to $1.0 trillion a year across industry. About 87% of that is indirect, such as lost revenue and missed orders. That indirect share is why the direct repair bill is a poor measure of the problem.
Single events can be very large. At LyondellBasell, an unplanned outage at its propylene oxide/TBA asset in Bayport, Texas, began in March 2026 and lasted about 13 weeks. Management estimated lost EBITDA at $25 million per week, or about $150,000 per hour. That works out to roughly $40 million in the first quarter and $250 million in the second. In the company's words, "The outage had an estimated EBITDA impact of approximately $250 million during the quarter."
Numbers like these explain why buyers now want evidence on the shop floor, not just a better detection rate. A prevented failure leaves no line on the profit and loss statement. You only see the value when the avoided outage shows up in availability and repair times.
Why experienced technicians used to close the loop
Maintenance organizations never really prioritized closing the loop from alert to repair. The gap was filled by people. An experienced technician read the alert, knew what was wrong, fixed it and remembered the failure for next time. That worked as long as the most experienced people stayed put.
They're not staying. In IoT Analytics' 2025 survey of 120 digital decision-makers in machine building, 43% named workforce skill gaps and lack of expertise as a critical or significant barrier to adopting AI. MaintainX co-founder Nick Haase estimates that half of maintenance and reliability professionals reach retirement age within about five years. As he put it, "50% of maintenance reliability professionals are going to be at retirement age in the next like 5 years. They're leaving the workforce all that tribal knowledge is leaving."
My read is that this is the real driver behind the loop-closing push. When the experts leave, the system has to carry what they knew, or repair times rise. The tools are being bought to replace tribal knowledge, not just to add dashboards.
Where the loop actually breaks
Part of the problem is organizational. In many manufacturers, reliability engineers and vibration analysts run condition monitoring, while maintenance planners run the CMMS, often with IT as owner. The two sides are bought from different vendors, and no single system records what technicians found in the field. Alerts travel by email or phone. Closeout notes are free text, often rushed or left blank, and "no fault found" is rarely recorded at all.
That last point matters more than it sounds. A technician's note such as "bearing replaced, outer race damage confirmed" or "no fault found" is exactly the label a diagnostic model needs. When the note never gets written, or never flows back, the model can't learn whether its alert was right.
Gousto, the UK-based meal-kit company, offers a useful counterexample. It connected its factory equipment, including older machines fitted with vibration sensors, to one data platform. Its CMMS now turns anomalies into work orders and sends them to engineers through an app. Over 18 months, mechanical availability rose from 70% to 98.5%, and mean time to repair fell from 1 hour to 15 minutes. Those are the kinds of figures that justify the integration work.
How the six segments divide the loop
IoT Analytics breaks the loop into six steps: detect, diagnose and prioritize, create and plan the work order, execute, close and document, and validate and learn. Its six market segments map onto that chain. The three sensing segments (wireless, wired and portable) handle detection. The three software segments take over from there. Standalone analytics diagnoses faults and recommends a fix. APM decides which issues matter most. CMMS plans, executes and documents the work.
The interesting development is that every segment is now reaching into its neighbors, mostly through product extensions and integrations. Sensing vendors are moving toward repair. Software vendors are moving toward detection. Few are doing it alone.
Wireless sensing: pushing past the alert
Wireless specialists used to stop at the alert. They don't anymore. Most now bundle sensors, software and expert diagnosis into one subscription, then push findings into the customer's work order system or supply their own CMMS. Nanoprecise, Waites, KCF Technologies and Augury each integrated with CMMS vendor MaintainX between October 2025 and March 2026.
The Waites integration is the notable one. Technician updates sync back to Waites' analysts, which makes it one of the few cases where the learning step actually closes. A sales engineer at a wireless vibration monitoring specialist described the basic workflow this way: "When our AI sensors detect a specific failure mode, such as pump cavitation, our platform opens a work order in the connected CMMS (e.g., MaintainX, SAP) or in our own CMMS." That's the pattern most wireless vendors are copying.
Wired sensing: moving toward the repair
The wired sensing segment is forecast to grow from $1.4 billion in 2025 at a 6% CAGR to $2.1 billion by 2032. It's the slowest of the sensing segments, but its vendors are also reaching for execution. ifm electronic's moneo Asset Health identifies the likely cause of a fault and creates a maintenance ticket with a repair recommendation.
SKF goes further on critical machines. It links condition monitoring with lubrication, alignment, bearing replacement and on-site maintenance support. It also takes responsibility for reliability outcomes through performance-based contracts. That's a different business model from selling sensors and software, and it means the vendor carries the repair risk too.
Standalone analytics: from prediction to prescription
Analytics vendors are adding the likely root cause and a recommended repair to each alert. Siemens (Senseye), Augury and Treon all showed such features in 2025 and 2026. A prediction alone doesn't reduce downtime. A diagnosis with a suggested fix gets a technician moving sooner.
To turn recommendations into work, these tools need to connect to execution. In July 2026, Augury partnered with Rockwell Automation so that Augury's alerts automatically create work orders in Rockwell's Fiix CMMS. The segment is forecast to grow from $1.1 billion in 2025 at a 22% CAGR to $4.2 billion by 2032.
CMMS: holding the work and the feedback
The CMMS is where work orders are planned, executed and closed, and where technicians record what was actually wrong. That makes it the natural home of the learning step. It's also why CMMS vendors are moving upstream. MaintainX showed a pressure-threshold trigger that opens a work order at IMTS 2026. Rockwell Automation connects machine data from its control systems to its Fiix CMMS.
The CMMS segment is forecast to grow from $1.9 billion in 2025 at a 13% CAGR to $4.6 billion by 2032. That's faster than the 12% annual growth it posted in 2022–2025. One sensing executive's comment captures the gap: "What many sensing companies do not provide typically is that closed loop with the work being executed and learning from it."
Few vendors cover every step
The leading vendors include Baker Hughes, IBM, Emerson, SAP, Siemens, ABB, SKF and GE Vernova, alongside fast-growing specialists such as I-care, Augury and Tractian. Most cover one or two steps and lean on partners for the rest. That's why cross-layer integrations have become so common.
IoT Analytics' Smart Maintenance Vendor Database 2026 shows how specialized the field is. Of 597 classified vendors, 76% offer only one of the six solution categories, and only 7% offer three or more. A category-specialist strategy is still the norm, and the loop gets closed through stitching.
Four routes to a closed loop
IoT Analytics sees vendors taking one of four routes to offer a closed loop. They can build the missing steps in-house, as Tractian has done. They can integrate with other products, as Augury, Waites, KCF and Nanoprecise have done with MaintainX. They can partner, as Rockwell Automation did with Augury. Or they can acquire, as Autodesk did when it bought MaintainX for $3.6 billion.
Siemens, Schneider Electric and Rockwell Automation sit among the top 20 vendors by market share and are profiled in depth in the report. MaintainX is one of the fastest-growing challengers. Each is investing heavily in closing the loop, but they're taking different paths to it.
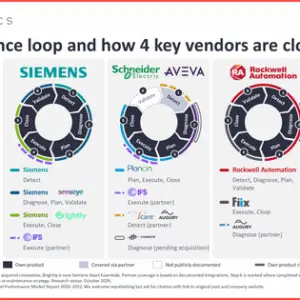
Siemens covers steps one through five with its own products. It combines its condition monitoring hardware with Senseye analytics and Brightly CMMS, both acquired in 2022. Built-in Industrial Copilots and AI agents across Senseye and Brightly now translate raw alerts into root-cause diagnoses, repair instructions and automated work orders. For field execution, Siemens tied its digital twin and production intelligence to IFS's AI-native EAM and field service management in June 2026.
Schneider Electric covers the software side, steps two through five, through AVEVA for analytics and APM and Planon for CMMS. It doesn't offer its own monitoring hardware within the report's scope, so it relies on partners such as I-care and Augury for machine data. Its pending acquisition of Cognite, agreed in 2026 for $3.1 billion, would add an industrial data and AI layer on top of AVEVA APM.
Rockwell Automation covers steps one through five with its own products. It pairs its sensing and analytics with Fiix, the CMMS it acquired in 2020. On July 14, 2026, Rockwell introduced Fiix MAX, an embedded AI maintenance assistant that surfaces asset history, parts context and work instructions inside the CMMS workflow. Later that month it partnered with Augury to connect Augury's Reliability Agent to Fiix MAX, so validated machine-health issues can generate prioritized work orders with root-cause diagnoses and recommended repair steps.
MaintainX starts from the CMMS, covering steps three through five, and relies on partners for detection and diagnosis. Its four wireless integrations are the backbone of that approach. Since May 2026, Autodesk has owned MaintainX, which could also feed field data back into product design. In the Waites and KCF integrations, technician feedback flows back to the sensing vendor, so MaintainX is the only one of the four where the learning step is documented.
AI as the orchestrator
Until recently, AI in maintenance mostly meant anomaly detection. That's changing. Vendors are adding agents that act on an alert and coordinate what follows, from the work request through to the technician and spare parts. IBM's Maximo Condition Insight analyzes asset data, work orders and failure modes. SAP's agents turn asset health signals into pre-filled maintenance requests. Bosch's Smart Maintenance Agent allocates technicians and spare parts. Siemens and Rockwell Automation embed AI assistants in their CMMS products.
Adoption is still early. Only one in five process plants in IoT Analytics' survey uses AI to predict failures. That gap between what vendors are shipping and what plants are running is worth watching.
Where the real limits are
IoT Analytics' central argument is that CMMS vendors are becoming the key to an automated loop. The reason is simple. The repair is planned, carried out and documented in the CMMS. Without it, a sensor or analytics vendor can't show that its alerts lead to repairs. The loop only closes when the technician's findings go back into the model. That tells the model whether an alert was right or a false alarm, so the next one improves.
The bigger constraint, though, is data. AI can only close the loop if it gets the right data, and that data sits in sensors, the CMMS, spare parts systems and often in technicians' heads. In many plants these sources aren't connected, and asset records are incomplete or out of date. An AI agent working from that data will create the wrong work orders or learn the wrong lessons. Poor maintenance data ranks among the five most pressing adopter challenges in the report, alongside the shortage of skilled labor.
That's why IoT Analytics argues plants need the basics first: connected systems, clean asset data, and work orders that get carried out and properly closed. Only then can AI learn from each repair. I'd agree that the groundwork is where most projects will stall.
How much autonomy to hand over
The next big debate is how much autonomy AI should have. Vendors are already taking opposite positions. Tractian positions itself as AI-first and lets its AI diagnose faults without a human analyst reviewing each alert. Waites and AssetWatch emphasize human experts before an alert reaches the customer. Both approaches face the same test, because one false alarm can badly damage a plant's trust in the system.
IoT Analytics maps where vendors including Waites, I-care and Tractian sit on a five-level scale of AI autonomy, from human-only to AI-only. The analysts' view is that plants will hand more of the loop to AI only once vendors can show a track record of correct alerts and completed repairs. I think that's the right order. Trust builds from documented outcomes, and the closed-loop data is what creates that record.
Maintenance is one of several loops
Maintenance isn't the only place this pattern is showing up. Across industrial operations, the same sequence of sensing, deciding, acting and learning applies in several spots. Along the value chain from engineering to maintenance, IoT Analytics sees early signs of at least six such loops. What agentic AI changes is that vendors can now close these loops in ways they couldn't before, which is why the discussions are happening now.
Adoption will still be slow. IoT Analytics expects closed-loop systems to take years to reach the mainstream in most of these areas, because manufacturers tend to be conservative and slow to adapt, even when the technology is ready. That's a useful reality check for anyone reading vendor roadmaps.
What to watch next
If you're evaluating tools, the practical question is simple: who owns the last step? Ask whether a vendor's alerts create work orders, whether closeout notes come back as structured data, and whether "no fault found" gets recorded. If the answer is no, you're buying detection, not a loop.
The market data points the same way. CMMS and wireless sensing are the segments to track, because that's where the loop-closing deals are landing. Expect more integrations between sensing specialists and CMMS platforms, and more agents that draft work orders from alerts. The unresolved question is who gets the learning step right, and at what level of AI autonomy plants will accept it.