2027 Component Supply Outlook: Memory, MLCCs and Power Devices Face Constraints
- adam-fleischer
- 736 reads
Memory and selected MLCCs, MCUs and power devices look tight for 2027. Plan around exact part availability and build qualified alternatives into the design.
For a controller scheduled to ship in 2027, the parts most likely to upset a spring cost model are memory, high-capacitance MLCCs, selected MCUs and power devices. Forecasts point to continued pressure in several of those categories, with meaningful differences between product types and suppliers. A late-year easing in some memory prices remains possible, but it’s a weak basis for an early 2027 build plan.
That matters before the architecture is locked. DDR4 or LPDDR4 selection, memory density, eMMC choice, MCU family and power-stage components can all be difficult to change later. The practical response is to check availability by exact part number, use current supplier quotes for budgets and give the design room for qualified alternatives.
Market growth is concentrated in memory
World Semiconductor Trade Statistics’ Spring 2026 forecast projects the semiconductor market will grow roughly 27% in 2027, from USD 1.5 trillion to about USD 1.9 trillion. Memory accounts for nearly two-thirds of the projected USD 400 billion increase, rising 32% to about USD 1 trillion. Logic is forecast to grow 27% and micro components 20%; discretes, sensors, analog and optoelectronics are forecast to grow between 5% and 7.6%.
For board designers, that split helps explain why aggregate market growth doesn’t mean broad component availability. Memory demand is drawing much of the expansion, while several common industrial-board categories have a more modest growth outlook. Even within memory, conditions differ between DRAM, enterprise SSDs, consumer NAND and embedded storage.
DRAM pressure may persist through early 2027
TrendForce expects conventional DRAM contract prices to rise 10 to 15% quarter over quarter in Q4 2026. The pace is slower than earlier in the year, but its November 6 update said price increases would “gain further momentum” in Q1 2027. Micron’s September 30 guidance describes memory and storage supply and demand as “much tighter” in calendar 2027 and 2028 than in 2026. CEO Sanjay Mehrotra said more than 75% of the company’s 2027 output was already committed. SK hynix said in October that long-term agreements covered more than 50% of its 2027 and 2028 capacity.
Gartner forecasts DRAM price relief from late 2027 into the first half of 2028, so the outlook isn’t uniform. Micron expects its first Idaho fab to begin wafer output in mid-2027, with meaningful shipments from its Tongluo facility around the same time. But a new fab takes a few quarters to reach meaningful output after production begins. For early-year builds, continued pressure is the safer assumption; later production may have more room for easing.
DDR4 and LPDDR4 add a product-lifecycle concern. Micron sent end-of-life notices to PC and data-center customers in June 2025, while reportedly continuing supply for long-term automotive, industrial and networking customers. In May 2026, it started 1-alpha DRAM manufacturing at its Manassas, Virginia, facility for long-lifecycle versions of both memory types, with qualified production expected by the end of 2026. Designers should verify supply and lifecycle status for the specific grade and density they need.
NAND forecasts diverge by use case
TrendForce projected NAND contract prices would rise 15 to 20% quarter over quarter in Q4 2026, with enterprise SSDs the memory category where it expected price growth to accelerate. Client SSD pricing is more flexible. Demand for eMMC and UFS is weaker as PC makers and smartphone brands draw on existing inventory.
For industrial eMMC, forecasts for 2027 disagree. TrendForce expects NAND supply to loosen in the second half, while Micron expects the industry to remain constrained through both 2027 and 2028. Softer consumer demand doesn’t establish that industrial-grade parts will be available. Check inventory and lead time on the exact eMMC part number, and treat a late-2027 price decline as an upside case in the cost model.
MLCC availability depends on capacitance and voltage
TrendForce reported in September that leading Japanese and Korean suppliers were shifting capacity away from consumer MLCCs toward AI applications. It expects mid- to high-capacitance consumer parts to tighten. The same update said Murata will discontinue some general-purpose GRM consumer types and some automotive-grade parts. Orders are accepted until 2028, with final shipments in 2029, so affected GRM part numbers need review well before a design reaches production.
Lead times vary sharply by part class. TrendForce reported standard-case lead times of 14 to 18 weeks in August, compared with 15 to 20 weeks for high-capacitance and high-voltage parts. DigiKey data put some Samsung Electro-Mechanics high-capacitance parts near 40 weeks. Samsung Electro-Mechanics raised prices by 30% across its MLCC portfolio on August 1. TrendForce’s October update forecast the high-end shortage to continue through the first half of 2027; Murata said new capacity was unlikely before 2028.
That makes case size, voltage rating and capacitance part of the sourcing decision. A stocked alternative still needs electrical qualification: capacitance under DC bias can differ from the nominal value, and a footprint match alone doesn’t establish equivalent performance.
Selected MCUs and power devices carry price and lead-time risk
STMicroelectronics said demand remained well above supply in its Q3 2026 results and that distribution inventory continued below its standard target. TrendForce News, citing EE Times China, reported that prices for some ST automotive MCUs had already risen 15 to 20% before a third price increase in August. A November report said selected products were due for another increase from January 1, 2027. These figures concern selected families; they shouldn’t be applied indiscriminately to every MCU.
Power-device lead times were generally above 30 weeks in TrendForce News’ August report, with some reaching 52 weeks. The report also put Infineon’s July increase for automotive power devices at 10 to 20%. On November 10, Infineon CEO Jochen Hanebeck said lead times continued to stretch, and the company reported emerging supply tightness in high-performance SiC products and high-power modules. Ask suppliers for current lead times and allocation terms for the exact device before finalizing the schematic.
Put sourcing options into the design
For memory, start with densities and packages offered by at least two manufacturers. Check which memory types the processor supports in case the preferred option tightens. Several manufacturers offer eMMC in the JEDEC-standard 153-ball BGA package, which can give a design a path to qualified second sources. Budget from current quotes with room for further increases; model late-2027 DRAM relief as a favorable scenario rather than a baseline.
In the power stage, favor MLCC values and case sizes that multiple manufacturers stock. For MOSFETs, a common package such as 5 x 6 mm DFN can make alternatives easier to evaluate, provided the pinout matches and the voltage, current and thermal ratings suit the design. Confirm gate-drive requirements and safe operating area before treating a substitute as qualified.
An MCU family with pin-compatible variants across memory densities offers flexibility within one manufacturer’s range, but it doesn’t add a second supplier. A pin-compatible device from another manufacturer provides a separate supply path only after checking pin functions, peripherals and boot behavior. A hardware abstraction layer can reduce firmware changes if a switch becomes necessary.
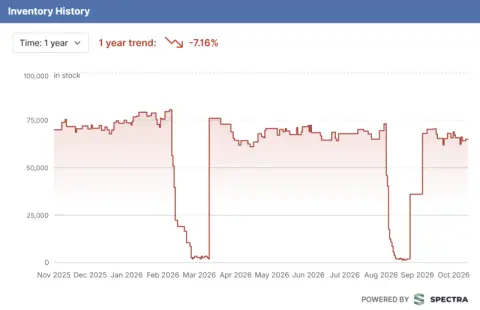
Before layout, review lifecycle status and 12-month inventory history for each critical part. Load the full BOM into a parts-management tool to identify components marked not recommended for new designs or end of life, then confirm unclear statuses with the manufacturer. For Q1 2027 BOM freezes, put memory, high-capacitance MLCCs, MCUs and power devices on a watchlist. Rework the cost model around flat or rising prices, and keep the alternatives technically qualified before the design is committed.